Buying a home usually involves one of the largest financial commitments a person will make. For many buyers, choosing the right mortgage can be just as important as finding the property itself.
Two of the most common mortgage options in the United States are FHA loans and conventional loans. Both can be used to finance a home purchase, but they have different eligibility rules, mortgage insurance requirements, down-payment structures, and credit standards.
An FHA mortgage is insured by the Federal Housing Administration and is designed in part to make homeownership accessible to borrowers who may have difficulty qualifying for some conventional financing. A conventional mortgage is not insured by the federal government and is typically offered through private lenders under their own underwriting requirements.
Neither option works the same way for every borrower. The better fit depends on factors such as credit history, available savings, income, debt obligations, the property being purchased, and how long the borrower expects to keep the mortgage.
Read:What is the difference between Home Equity Loan vs. HELOC
What Is an FHA Loan?
An FHA loan is a mortgage issued by an approved lender and insured by the Federal Housing Administration.
Because the federal government provides insurance to the lender, FHA financing can accommodate borrowers who may not meet the stricter requirements associated with some conventional mortgages.
One feature that attracts many first-time buyers is the possibility of making a relatively small down payment when the borrower meets the applicable credit requirements.
FHA financing can therefore be useful for buyers who have limited savings or a less established credit history.
However, a lower entry barrier does not mean the mortgage is inexpensive in every situation. FHA loans generally involve mortgage insurance, and borrowers need to consider that cost when comparing the overall financing.
What Is a Conventional Loan?
A conventional mortgage is a home loan that is not insured or guaranteed by the federal government.
These mortgages are commonly offered by banks, credit unions, mortgage companies, and other private lenders. Conventional loans may be available with relatively low down payments, although the specific requirements depend on the lender and the program.
Borrowers with strong credit, stable income, manageable debt, and sufficient savings may qualify for competitive conventional mortgage terms.
Unlike FHA financing, conventional mortgages do not follow one single government-insured structure. Requirements can vary between lenders and between different conventional loan programs.
FHA vs. Conventional: The Main Differences
The most important differences usually involve credit requirements, down payments, mortgage insurance, property standards, and borrowing costs.
| Feature | FHA Loan | Conventional Loan |
|---|---|---|
| Government insurance | FHA-insured | No federal mortgage insurance |
| Down payment | Can be as low as 3.5% for eligible borrowers | Can be as low as 3% for some programs |
| Credit requirements | Often more flexible | Usually stronger credit is preferred |
| Mortgage insurance | FHA mortgage insurance generally applies | Private mortgage insurance may apply with a smaller down payment |
| Property requirements | FHA appraisal/property standards apply | Lender and program requirements apply |
| Typical borrower | Buyers who may need more flexible qualification | Borrowers with stronger credit and financial profiles |
| Mortgage insurance removal | Different FHA rules apply depending on loan terms and down payment | PMI can generally be cancelled under applicable conditions |
The exact terms can change according to the borrower, lender, loan program, and current regulations.
Down Payment: Which Mortgage Requires Less?
Down-payment requirements are often one of the first issues buyers consider.
Eligible FHA borrowers may qualify for financing with a 3.5% down payment when they meet the applicable credit requirements. Borrowers with lower qualifying credit scores may face a larger required down payment.
Some conventional programs also permit down payments as low as 3%, making the difference between the two options smaller than many buyers assume.
For a $300,000 home, a 3% down payment would be $9,000, while 3.5% would equal $10,500.
However, the down payment is not the only cash required to purchase a property. Buyers may also need money for closing costs, prepaid expenses, inspections, moving costs, reserves, and other expenses.
Consequently, prospective homeowners should calculate the complete amount of cash required rather than focusing exclusively on the initial deposit.
Credit Score Considerations
Credit history can play an important role in mortgage approval.
FHA financing is often associated with more flexible credit standards than conventional mortgages. This can make it an option for borrowers whose credit history is less established or includes previous financial difficulties.
Conventional lenders may place greater emphasis on credit quality, particularly when determining pricing and eligibility.
A higher credit score can also affect the cost of borrowing. Two applicants purchasing similar homes may receive different mortgage offers because their financial profiles are different.
It is important to remember that a credit score alone does not determine approval. Lenders can also review income, employment, debt, assets, payment history, and other information.
Read: Best personal loans lender in Nigeria
Mortgage Insurance: A Major Difference
Mortgage insurance is one of the most significant distinctions between the two loan types.
With an FHA mortgage, borrowers generally pay mortgage insurance premiums. Depending on the loan structure and down payment, this can include an upfront premium and an annual premium paid over time.
Conventional mortgages may require private mortgage insurance (PMI) when the borrower has a relatively small down payment.
One important difference is how the insurance can eventually end.
For many conventional mortgages, PMI can generally be cancelled when the borrower meets the applicable equity requirements and makes the required request. It may also terminate automatically under certain federal rules.
FHA mortgage insurance follows different rules. For some FHA loans, the annual mortgage insurance premium can remain for the life of the loan unless the mortgage is refinanced or otherwise paid off.
Because insurance costs can accumulate over many years, borrowers should compare the long-term expense rather than looking only at the initial monthly payment.
FHA Appraisal and Property Requirements
An FHA-financed property must meet certain standards related to safety, security, and habitability.
The FHA appraisal process is intended not only to establish an estimated property value but also to identify certain conditions that may affect the property’s eligibility for FHA financing.
This can matter when purchasing older homes or properties requiring substantial repairs.
Conventional financing can also involve property standards and appraisal requirements, but the process and criteria are not identical to those associated with FHA financing.
A buyer interested in a particular property should therefore discuss its condition with the lender before assuming that any mortgage type will work.
Debt-to-Income Ratio and Affordability
Mortgage lenders generally examine the relationship between a borrower’s debt obligations and income.
This is commonly expressed through a debt-to-income ratio (DTI).
For example, someone earning $7,000 per month who has substantial payments for credit cards, student loans, car financing, and other obligations may have less borrowing capacity than another person with the same income but fewer debts.
FHA underwriting can provide flexibility in certain circumstances, but lenders still need to establish that the borrower has a reasonable ability to repay the mortgage.
Conventional lenders also examine income and debt obligations when assessing affordability.
Homebuyers should calculate their expected mortgage payment together with property taxes, homeowners insurance, utilities, maintenance, and other housing expenses.
Read:Lists of Banks and Microfinance Banks Offering Business Loans to SMEs in Nigeria
Interest Rates and Overall Cost
It is easy to compare mortgages by looking only at the advertised interest rate. That approach can be misleading.
The actual cost of a mortgage can include:
- Interest
- Mortgage insurance
- Origination charges
- Discount points
- Closing costs
- Appraisal fees
- Other lender charges
- Property taxes and insurance
A mortgage with a lower interest rate may not necessarily be cheaper if it carries higher fees or insurance costs.
Borrowers should compare the annual percentage rate (APR) and the estimated total borrowing costs, while also reviewing the loan’s specific terms.
The length of time a buyer expects to keep the mortgage can also influence which structure makes financial sense.
FHA Loans May Be Useful for Some First-Time Buyers
FHA financing is commonly considered by first-time homebuyers because the program can offer more flexible qualification features.
It can be particularly relevant for someone who has limited savings or a credit profile that does not fit comfortably within a conventional lender’s requirements.
However, being a first-time buyer does not automatically make FHA financing the appropriate choice.
A buyer with strong credit and sufficient savings may find that a conventional mortgage offers different pricing or mortgage-insurance characteristics.
The right comparison should therefore be based on the borrower’s actual financial circumstances rather than simply whether the person has purchased a home before.
When a Conventional Mortgage May Be Attractive
A conventional mortgage may appeal to borrowers with stronger credit, stable income, manageable debt, and enough savings to meet the required down payment and closing expenses.
One potential advantage is the treatment of PMI. For eligible conventional loans, PMI can generally be removed once the borrower reaches the required equity level and satisfies the applicable conditions.
This can reduce the long-term cost of the mortgage compared with a structure where mortgage insurance continues for a longer period.
Again, the actual benefit depends on the interest rate, loan amount, fees, down payment, and other terms offered to the borrower.
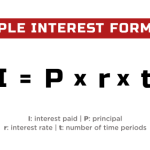
Read: Understanding Interest Charges and Their Impact on loan and Debt Repayment
Example: Comparing Two Borrowers
Consider two people purchasing similar $300,000 homes.
Borrower A has a limited down payment and a less established credit history. An FHA mortgage may provide a financing route that fits those circumstances, although mortgage insurance and other costs must be considered.
Borrower B has stronger credit, lower existing debt, and enough savings for a larger down payment. A conventional mortgage may provide different pricing and PMI options.
Neither example establishes that one mortgage is universally cheaper. The final cost depends on the individual loan offers.
This is why buyers should request actual loan estimates rather than making a decision from general assumptions.
FHA vs. Conventional: Questions to Ask Before Choosing
Before selecting a mortgage, prospective borrowers should consider:
- How much money is available for the down payment?
- What is the current credit profile?
- How much existing debt is being carried?
- What will the complete monthly housing cost be?
- How much will mortgage insurance cost?
- Can conventional PMI eventually be cancelled?
- What are the lender’s closing costs?
- How long is the borrower likely to keep the mortgage?
- Does the property meet the relevant financing requirements?
- What is the total cost over the expected period of ownership?
Getting several loan estimates can make these comparisons more meaningful.
FHA vs. Conventional: Which One Should You Choose?
The choice between FHA and conventional financing depends on the borrower’s circumstances.
FHA loans can provide an option for buyers who need more flexible qualification standards and a relatively small down payment. The trade-off may include mortgage insurance costs and specific program requirements.
Conventional mortgages may suit borrowers with stronger credit and financial profiles, particularly when they can benefit from competitive pricing or the potential to eliminate PMI under applicable rules.
The most useful comparison is not simply the interest rate or minimum down payment. Buyers should consider the complete cost of the mortgage, including insurance, fees, cash required at closing, and the expected repayment period.
Final Thoughts
FHA and conventional loans serve different segments of the U.S. mortgage market. Understanding the distinction can make it easier to evaluate financing offers and avoid focusing on one feature in isolation.
FHA financing may provide greater flexibility for certain borrowers, while conventional mortgages can offer different advantages for buyers with stronger credit and more available resources.
Before committing to either option, review the loan estimate carefully, compare multiple lenders where possible, and calculate the full cost of homeownership. The mortgage that appears attractive at first glance may have additional costs that become significant over several years.
A well-informed mortgage decision starts with understanding not only how much you can borrow, but also how much the borrowing will cost and whether the repayment fits comfortably within your long-term budget.
Contact us; Kokobest04@gmail.com
- FHA vs. Conventional Loans: What Is the Difference? - October 3, 2026
- What is the difference between Home Equity Loan vs. HELOC - October 1, 2026
- Best personal loans lender in Nigeria - September 29, 2026